It only looks closed

Denton bookkeeping. The CPA alternative.

Four taps. Two invoices, and a code from the next city.

Two invoices. The code still has to be read.

Question 1 of 4

What is the matched month hiding?

Question 2 of 4

What is on a sale inside the city?

Question 3 of 4

Did October rename this city?

Question 4 of 4

When is the month actually finished?

A quick check

Did a pasted code become an attest demand?

An audit, a review, or a compilation is a report a lender, an investor, or a board relies on. Two invoices and a transit half are a monthly close. Most owners in this city are never required to produce an attest report.

The Denton alternative for a pasted code is a Tax CFO.

Steven Palmieri works as a Tax CFO on this door. He keeps the books, sets payroll up on the provider you run, and will not call a month closed until both invoices and the city code have been read. The free call says whether the half percent is missing or the sale was simply outside the city.

You will be talking to the Steven Palmieri practice.

Next you pick a time for a free video call with the Steven Palmieri practice. Nothing to sign, nothing to pay.

Prefer to read first? It's all below ↓

CPA and Bookkeeping Denton AlternativeCPA Denton keeps the books current

We keep the books, set payroll up, reconcile the month, and prepare the return with statements you can read, alongside Steven Palmieri, Tax CFO and the Entrepreneur's CFO.

A month can match the bank and still carry a code from the wrong city. We read both invoices before we call it closed.

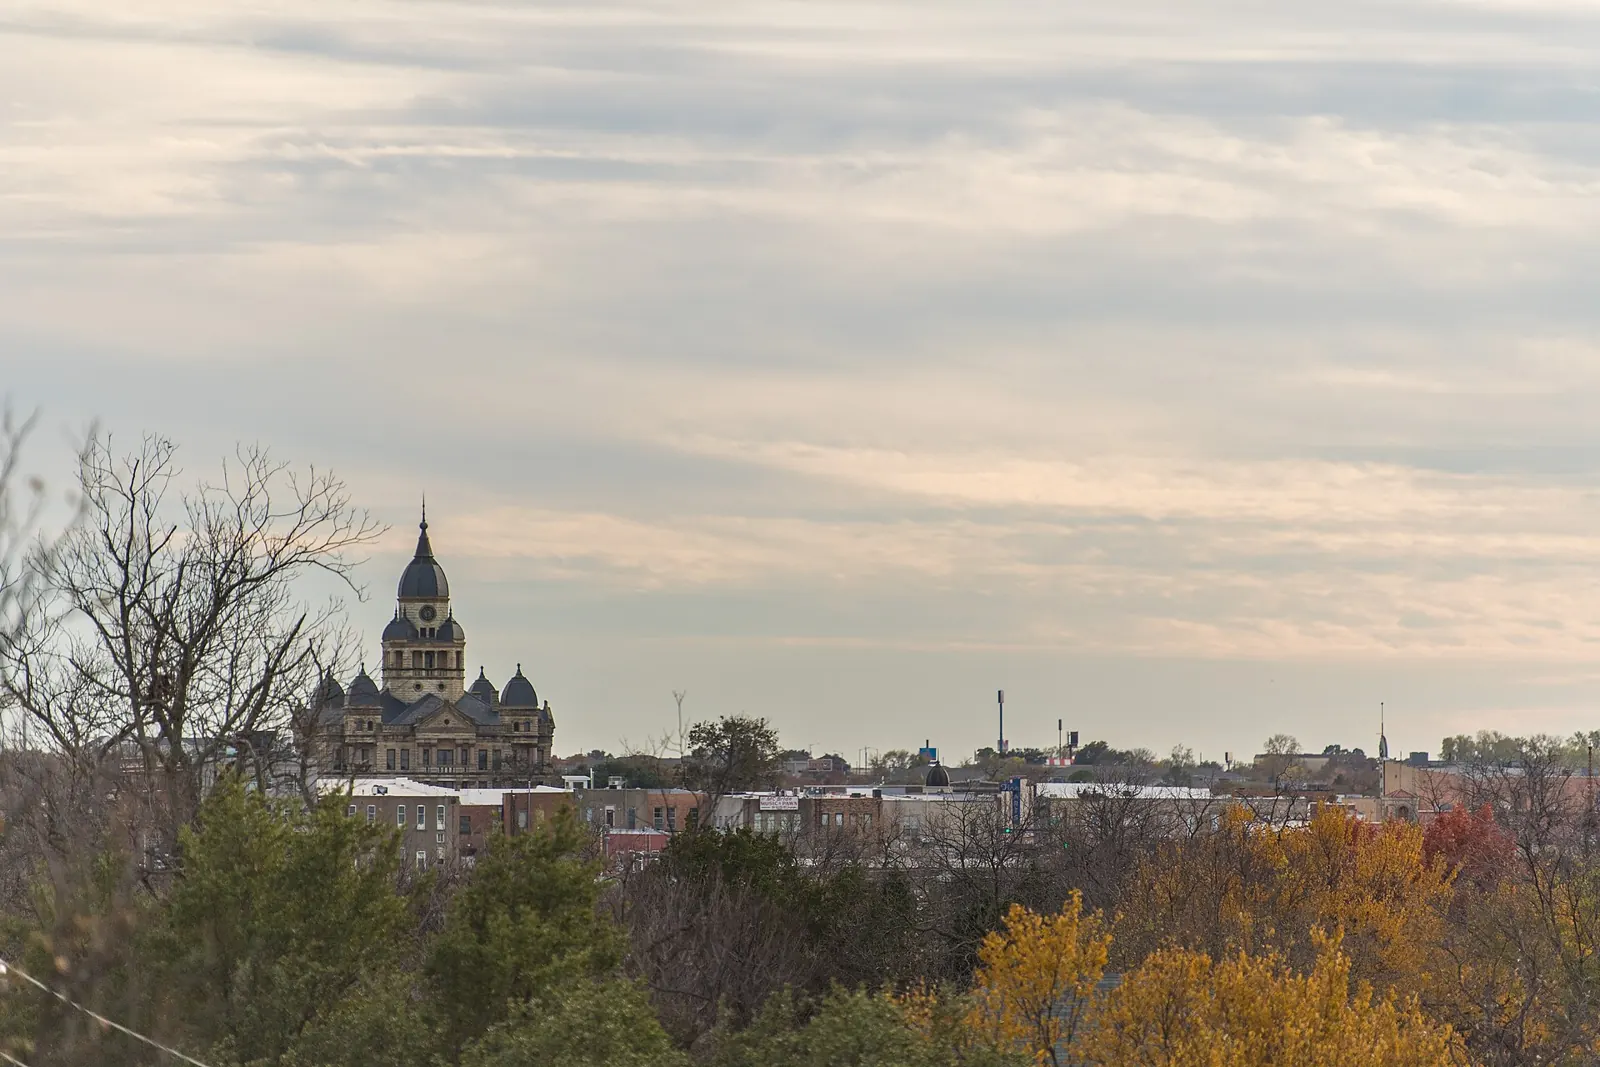
The Denton County courthouse on the downtown square
Saturday on the square is ours too. The weekend's two invoices still land in the month they were paid.
A person writing beside a laptop while two weekend invoices wait to be named.
Start this month

Start with an open month.

Steven Palmieri, Tax CFO

You will be talking to the Steven Palmieri practice.

The Tax CFO way with two invoices

A bookkeeper records both invoices. The Tax CFO asks why there were two, whether the code on the sale was the right city, and whether the month that looked closed was actually closed. Matching the bank is where that question starts.

A person at a laptop while the bank match, a wrong city, and a closed month take their turn.

Six troubles a month has

Open one.

  1. 1Two bills for one weekend do not match.

    We read both bills against the deposit.

    The sale, the tax, and a payout that is not a sale have to be three lines before the month can close.

  2. 2A code was pasted from a city next door.

    We ask which city the sale actually happened in.

    A neighbor city can leave off a half percent the sale still owes, or add one the sale does not.

  3. 3The bank matched and a class is blank.

    We treat the blank as still open.

    A matched balance does not name the tax, the owner draw, or the transfer that rode along inside it.

  4. 4Payday has no company yet.

    We open the payroll company and stop.

    The login stays with you. Later paydays are yours to run once the path into the books exists.

  5. 5October is here and a purchase is undecided.

    We name what the year can still change.

    October still lets an owner choose pay, a large purchase, and the next estimate, because the year has not locked.

  6. 6A notice arrived about a year that never closed.

    We gather what the notice names.

    Any relief comes later, once the records sit in one stack. Nothing on this card predicts a smaller balance.

Name this trouble

Steven PalmieriSteven Palmieri, Tax CFO

Steven Palmieri, Tax CFO.

The Entrepreneur's CFO. The books get a name before the return is opened.

Meet Steven

Bring the open month.

One month shows whether the rest of the year is the same kind of trouble.

Steven Palmieri, Tax CFO

You will be talking to the Steven Palmieri practice.

The two invoices.

A weekend can produce a shop ticket, a card batch, and a deposit that arrives on Monday. The ticket is what the customer agreed to pay. The batch is what the processor says it will send. The deposit is what the bank actually received, often after a fee the batch already subtracted.

Those three figures are not three sales. One of them is the sale. One of them is the tax collected on that sale. One of them is a payout that is not a sale at all. If the payout is posted as income, the month looks richer than the shop was, and the tax collected has nowhere to sit.

We read both invoices before we call the month closed. The sale lands in the week the customer paid. The fee lands as its own line. The tax collected lands as money held for the state and the city, not as extra revenue. A payout that is only a transfer between the processor and the bank does not get a second life as a sale.

Owners often keep the customer copy and lose the processor summary, or the other way around. Either copy alone will reconcile the bank and still misname the month. Bring both. If one of them is a photo on a phone, that is enough to start. Some of the shops on the square have been open since the 1940s, and we share that Saturday the way a neighbor does. A ticket from one of those shops still has to name the month the customer paid.

Closing the month.

The bank feed can match a balance and still leave the story blank. A matched total means the dollars in the software agree with the dollars at the bank. It does not mean each dollar was given a class, a customer, or a tax code. TS-028 is the shape of that monthly close. The feed is the start, not the finish.

We treat a blank class as still open. A deposit with no class might be a sale, an owner contribution, a loan draw, or a refund from a vendor. Those four events do not belong on the same line. TS-047 is the reminder that money arriving is not automatically income. The close names which one it was.

A chart of accounts that grew by accident makes the blank class more likely. Old accounts stay on the list, new ones get added for a single vendor, and the next deposit has twelve places it could go. We archive the dead accounts and keep the live ones few enough that a person can choose. Choosing the account is itself the close.

Statements come after that naming. A profit report printed while classes are blank is a picture of the bank, not of the business. We would rather hand you a shorter report that you can explain than a longer one that only matches the ending balance. The fair and rodeo at the fairgrounds has drawn the town since 1948, and we enjoy that week the way anyone here does. A deposit from a fair weekend still has to be named in the month the ticket was paid.

Payroll setup.

Setting payroll up means opening the payroll company, connecting it to the books, and walking the first path from a payday into the right accounts. The login stays with you. Later paydays are yours to run, or a payroll company's to run. We do not stay on as the people who press the payday button each period.

The path matters more than the first check. Wages, withholdings, and the employer share have to land in accounts the monthly close already understands. If those accounts do not exist, the first payday creates a pile that the return will have to untangle. We build the path, watch one payday cross it, and stop.

Contractors are a different path from employees. A person paid without a payroll run still needs a record good enough for a year-end form. We set that record up beside the payroll company. We do not turn a contractor into an employee, and we do not turn an employee into a contractor to make a Friday easier. The downtown transit center and Medpark Station have been stops since 2011, and we ride that line the way a neighbor does. A fare and a shop sale are still two different lines when the month is named.

The return.

Filing from a year that is still open puts a signature on a guess. We prepare the return after the months agree with the bank and with each other. Estimates paid during the year are matched to the periods they were meant to cover. A notice about a year that never closed is a request for records, and it is not a promise that the balance shrank.

October has not locked the year, so a few choices can still move. Pay for the owner, a large purchase, and the next estimate can still move before the year locks. We name what the year can still change. This page quotes no savings figure, and it invents no outcome.

If the books are a year behind, the return is a year behind. The first conversation is about how many months are open, not about a tactic. Clean months are the tactic. Everything else waits its turn.

A good first month.

You send one open month, both invoices from the awkward weekend, and the bank export for that month. We return the month with the sale, the fee, the tax, and the payout on four different lines. You can see which line was the one that used to be missing.

The second month goes faster, because the accounts now exist. The third month is the one that starts to feel like a rhythm. Reports get useful around then, because three closed months can be compared and one closed month cannot.

What we actually do is keep the books, stand payroll up, close the month, hand over statements, and prepare the return. Signed reports have their limit written on the disclosures page.

Where to go next.

The half percent page is the one to read if a sale inside the city and a sale in the next city over produced different totals. The two invoices page is the one to read if a shop ticket and a card deposit refuse to match. The October page is the one to read if a large buy is still undecided.

The close page is national. It is about a blank class after the bank already matched, and it does not depend on which city collected the tax. The return page is national in the same way. The May page is the margin report, and that one is a state report with a May date.

Questions are collected on their own page. A time to talk is on the booking page, and the button above this fold opens the same conversation. Bring one month. We can tell from that month whether the rest of the year is the same kind of trouble.